|
Editor’s Note: Jeff Brown is the former tech executive who picked Nvidia in 2016 before it jumped 37,000% higher. He’s now recommending another AI stock that’s the same size Nvidia was 10 years ago. He calls it “Elon Musk’s One Stock Retirement Plan” because he believes Elon Musk is about to create massive demand for this company’s patented technology. Click here to see the details or read more below. Dear Reader, Make your calendar… By November 11, I believe Elon Musk is going to help trigger a historic rally in what could be… “The Only AI Stock You Need to Retire.” This little-known company has developed a technology… That can produce intelligence up to 1,000 times FASTER than regular AI. It’s the same size Nvidia was 10 years ago… Before shares skyrocketed 37,800%... And while I can’t guarantee you’ll become a millionaire... That was enough to turn $5,000 into an entire retirement nest egg of $1,895,000. I call this opportunity…. “Elon Musk’s One Stock Retirement Plan…” Because I believe Elon Musk is about to accelerate the AI revolution faster than ever… Creating massive demand for this company’s patented technology. Again, I believe this might be the only stock you need to retire. We have so much to look forward to, Jeff Brown,
P.S. If I could buy only one stock, this would be it… it might just be the perfect tech stock. It’s a leader in an AI breakthrough that’s protected by 150 patents… It’s a small company, unknown to most people… still in the initial phase of exponential growth… Plus, it has a near term catalyst that could send shares skyrocketing… starting November 11. Today’s editorial pick for you Shake Shack Stock Climbs as Profits Jump Nearly 32%Posted On Nov 05, 2026 by Ian Cooper 
Shake Shack (NYSE: SHAK) gave investors enough good news to look past a small sales disappointment. The quarter wasn’t perfect. Revenue fell slightly short of Wall Street’s forecast, and higher restaurant expenses put some pressure on profitability. But the broader picture was encouraging: Shake Shack is opening more locations, growing sales at existing restaurants, and turning that growth into higher earnings. Table of ContentsFor investors, that combination offered a reason to stick around for another serving. Shake Shack reported adjusted earnings of 40 cents per share, beating the 35-cent estimate. Revenue increased 15.2% from a year earlier to $423.3 million, slightly below the roughly $426 million expected. That distinction matters. Missing a forecast doesn’t necessarily mean business is weakening. Shake Shack still delivered double-digit revenue growth; sales simply came in a little below the number analysts had penciled in. Profit Growth Also Gave Investors Something to LikeNet income attributable to Shake Shack increased 31.9% to $16.5 million. Adjusted EBITDA, a profit measure that excludes interest, taxes, depreciation, amortization, and certain other items, rose 16% to $62.8 million. Its adjusted EBITDA margin edged up to 14.8% from 14.7% a year earlier. In Plain English, the company generated more revenue and more adjusted operating profit while keeping that profit measure broadly steady as a percentage of sales. That helps explain why investors could look past the modest revenue miss. The earnings result suggested Shake Shack’s expansion was producing benefits beyond a bigger restaurant count. More Customers Are Walking Through the DoorOne of the more encouraging details was what happened at existing restaurants. Same-Shack sales increased 2.5%. This measure tracks sales growth at comparable locations, helping investors see how established restaurants are performing without the boost from new openings. Customer traffic rose 0.8%, marking the fifth consecutive quarter of traffic growth. Shake Shack also extended its streak of positive same-Shack sales growth to 23 consecutive quarters. The traffic number deserves attention because restaurants can increase sales through higher prices even when fewer people visit. Positive traffic provides another source of growth: more customer visits. Shake Shack opened 21 company-operated restaurants and 16 licensed locations during the quarter. Across both types of restaurants, system-wide sales increased 12.8% to $644.8 million. That figure differs from reported revenue because it includes sales at licensed restaurants. Shake Shack records licensing revenue from those locations rather than counting all their restaurant sales as its own. The expanding footprint creates more opportunities to reach customers. Still, growth brings expenses, and this quarter showed why investors need to watch both sides of that equation. Restaurant-level profit increased 13.8% to $91.7 million, but the restaurant-level profit margin slipped to 22.5% from 22.8%. Put simply, restaurants generated more profit in total while keeping slightly less profit from each dollar of sales Higher operating expenses and investments in labor weighed on the margin. Lower food and paper costs helped offset some of that pressure. The Outlook Keeps the Growth Story MovingManagement reaffirmed its full-year 2026 revenue forecast of $1.6 billion to $1.7 billion. The $1.65 billion midpoint matches Wall Street’s consensus estimate. The company also expects low-single-digit same-Shack sales growth, alongside 60 to 65 company-operated openings and 40 to 45 licensed openings. That outlook points to continued expansion, with more measured growth at established restaurants. For investors, the next question is whether Shake Shack can keep attracting customers while managing the costs of a larger business. This quarter offered encouraging evidence, particularly through higher earnings and another increase in traffic. Keeping that momentum going and protecting restaurant margins would give shareholders more substance behind the rally. 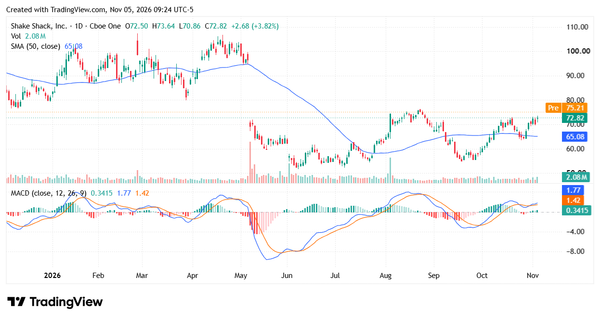
This is a PAID ADVERTISEMENT provided to the subscribers of StockEarnings Free Newsletter. Although we have sent you this email, StockEarnings does not specifically endorse this product nor is it responsible for the content of this advertisement. Furthermore, we make no guarantee or warranty about what is advertised above. Your privacy is very important to us, if you wish to be excluded from future notices, do not reply to this message. Instead, please click Unsubscribe. Stock Earnings, LLC
|


No comments:
Post a Comment