Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
When it hits, it will send shockwaves through the financial markets.
Regards,
Matt Insley Publisher, Paradigm Press
Today’s editorial pick for you
General Motors (GM) Unveils $20 Billion Buyback After Earnings Beat
Posted On Oct 20, 2026 by Ian Cooper
General Motors (NYSE: GM) earnings topped Wall Street’s expectations, revenue came in stronger than forecast, and the automaker raised its cash flow outlook. It also announced a new $20 billion stock buyback.
Table of Contents
And while GM delivered a solid quarter, rising costs and expectations for a weaker fourth quarter left questions about how much more the company can deliver this year.
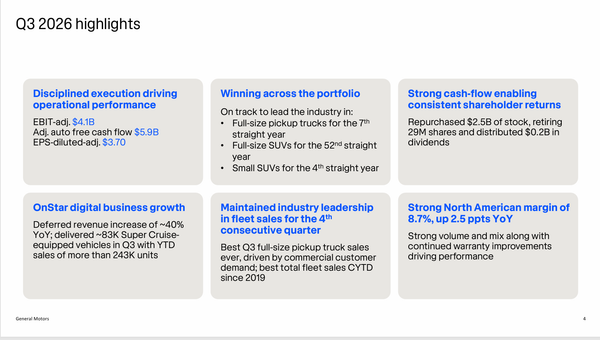
The company also improved on its results from a year earlier. Revenue rose about 3%, while adjusted earnings per share climbed roughly 32% from $2.80. Net income attributable to stockholders reached $3.3 billion, compared with $1.3 billion a year earlier. North America remained the company’s biggest source of profit. The region contributed about $3.6 billion of GM’s $4.1 billion in adjusted earnings before interest and taxes, or EBIT.
Those results demonstrate that GM’s core business is still generating substantial earnings. However, its heavy dependence on North America also makes consumer demand and production costs in that market especially important.
And, as noted by General Motors Chair and CEO Mary Barra:
“GM is performing well, and we are working hard to continue our momentum despite growing inflationary pressures through strategic investments in new products and services, and through improved quality and operating efficiency. Over the next several years, our portfolio will only get stronger as we complete the launches of the all-new 2027 Chevrolet Silverado and GMC Sierra light-duty pickups and follow them with our next-generation heavy-duty pickups, our next-generation full-size SUVs, all-new Cadillac sedans and crossovers, and more.”
GM Narrows Its Outlook as Inflation and Costs Rise
GM narrowed its full-year adjusted EBIT forecast to between $14.5 billion and $15.5 billion, compared with its previous range of $14 billion to $16 billion. Its adjusted earnings-per-share outlook moved to $12.75 to $13.75, compared with $12 to $14 previously. General Motors expects about $2 billion in commodity inflation costs, placing the figure at the high end of its previous forecast. Higher logistics expenses and costs for memory chips are adding pressure.
One encouraging development was GM’s higher adjusted automotive free cash flow forecast.
The company now expects $11.5 billion to $12.5 billion, up from $9.5 billion to $11.5 billion.
That money gives General Motors flexibility to invest in its business and return capital to shareholders.
In fact, the company’s new $20 billion buyback authorization follows completion of a $6 billion repurchase program. The company also declared an 18-cent per share dividend, which is payable on December 17 to shareholders of record as of December 4.
For investors, it helps to understand what a buyback can accomplish. When GM repurchases shares, it reduces the number outstanding, spreading its earnings across fewer shares. That can increase earnings per share even without an increase in total profit. However, the price it pays matters. Repurchasing shares at an attractive valuation can make better use of shareholder money than buying at an expensive price.
The authorization also does not mean the automaker will spend the money immediately. Investors should watch how quickly purchases happen and whether the company maintains enough financial flexibility to support vehicle launches and handle unexpected business challenges.
Can GM Sustain Its Earnings Growth and Cash Flow Momentum?
The good news — GM’s quarter offered real progress: higher earnings, stronger cash expectations and a substantial commitment to repurchases. The next test is whether those strengths can withstand mounting expenses.
At the end of the day, if General Motors can keep buyers interested, control expenses, and deliver on its stronger cash flow outlook, it would give investors more reason for confidence. The next quarter should offer a clearer picture of whether the company can keep that momentum going.
Today’s editorial pick for you
Tesla’s $43.5 Billion Cash Pile Faces a High-Stakes AI Test
Posted On Oct 20, 2026 by Grayson Cavern
Tesla (NASDAQ: TSLA) has a $43.5 billion cash pile, a growing energy business, and ambitious plans for robotaxis and humanoid robots. Yet its operating margin collapsed to 1.4% in Q2, just as capital spending accelerated. The company is attempting to build its next growth engine while its automotive business faces mounting pressure to deliver the profits that will pay for it.
Table of Contents
Tesla reports third-quarter earnings on Wednesday, October 21, after the market closes. The company-compiled analyst consensus calls for $28.34 billion in revenue and 45 cents in adjusted EPS. Revenue would be roughly flat year over year, while adjusted earnings would fall from 50 cents a share.
The stakes extend beyond an earnings beat. The company is committing more capital to AI compute, robotaxis, and robotics while investors debate whether its automotive economics can support those ambitions. This quarter needs to show that the core business can keep funding the transition.
Tesla’s Delivery Beat Needs to Reach the Bottom Line
Tesla delivered 486,532 vehicles in Q3, beating Wall Street’s estimate of approximately 462,000. Deliveries still declined 2.1% year over year from 497,099, according to the company’s Q3 production and delivery report. Production came in at 464,391 vehicles, around 22,000 below deliveries, allowing Tesla to work through inventory.
That is a useful volume result, but Q2 showed how little protection stronger sales provide when margins deteriorate. Revenue increased 26% year over year to $28.24 billion, yet operating income fell 57% to $398 million. Operating margin contracted to 1.4%, while adjusted EBITDA declined 4% to $3.27 billion. Tesla’s Q2 2026 details the pressure from lower average selling prices, reduced regulatory-credit revenue, and higher operating expenses tied partly to AI research and development.
Automotive gross margin excluding regulatory credits stood at 16.3% in Q2. With price competition limiting Tesla’s ability to push vehicle prices higher, manufacturing efficiency and product mix carry more weight in the earnings equation.
For Q3, I’m watching automotive gross margin, average selling prices, regulatory-credit revenue, and operating expenses. A delivery beat has already landed. The next catalyst is evidence that Tesla can turn those vehicles into stronger operating income.
The AI Bill Is Getting Bigger
Capital spending reached $5.79 billion in Q2, up 142% year over year. Operating cash flow of $4.70 billion could not cover that outlay, leaving free cash flow at negative $1.09 billion. Cash and investments ended June at $43.52 billion.
The latest Tesla Q3 analyst consensus projects approximately $7.77 billion in capital expenditures and negative $4.51 billion in free cash flow. For the full year, analysts expect capex of roughly $25.35 billion.
The spending supports Tesla’s expansion into AI compute, autonomous driving, and robotics. During the first half of 2026, the company more than doubled its onsite AI compute capacity in Texas. Cybercab production has begun, robotaxi operations are expanding, and Tesla is installing first-generation Optimus production lines in Fremont. The company also expects Tesla Semi and Megapack 3 production to begin this year.
These projects could eventually produce higher-margin revenue streams. For now, they require substantial upfront investment. Q3 cash flow and management’s updated spending plans will show how much financial flexibility Tesla retains as it builds those businesses.
Robotaxis Must Earn Their Valuation Premium
Tesla’s bull case increasingly depends on software and autonomous driving becoming meaningful profit centers. Active FSD subscriptions rose 56% year over year to 1.48 million in Q2. Services and Other gross profit also climbed $302 million sequentially to a record $648 million, reaching a 14% gross margin. Those figures provide early evidence of a business extending beyond vehicle sales.
The next earnings call should clarify whether robotaxi deployment is advancing toward scalable commercial operations and whether FSD adoption is translating into recurring revenue. Optimus offers another potential growth avenue, but production milestones alone cannot establish its eventual contribution to earnings.
Meanwhile, speculation around a potential Tesla–SpaceX combination has added another variable to the stock. But keep in mind, any transaction remains speculative, so the company’s operating results should carry more weight than merger chatter.
TSLA Needs to Reclaim Its Trend
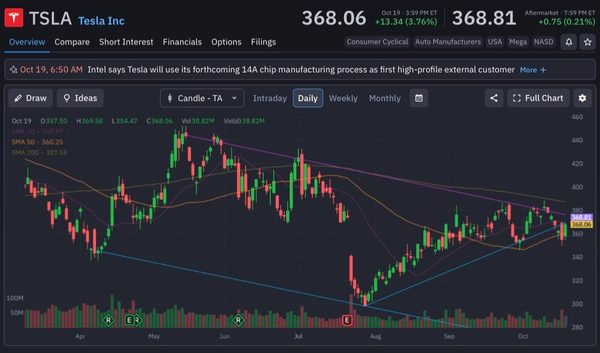
TSLA stock closed at $368.06 on October 19, up 3.76%. Its 20-day moving average sits at $369.97, the 50-day at $360.25, and the 200-day at $387.58.
The recovery from July’s low near $300 has improved the chart, but TSLA remains below its 200-day average and a descending trendline from the spring highs. Resistance around $378–$380 comes first, followed by $387–$390. On the downside, $350–$355 is a key support zone near the rising trendline.
Still A Buy…But
My stance is BUY, with profitability and AI execution as the catalysts. Tesla has demonstrated demand resilience, but the next leg higher needs stronger automotive economics and tangible progress toward monetizing AI. Improving margins alongside disciplined spending would strengthen the bull case. If cash burn accelerates while operating profitability remains thin, the stock could struggle to clear overhead resistance.


No comments:
Post a Comment